
QUICK SUMMARY
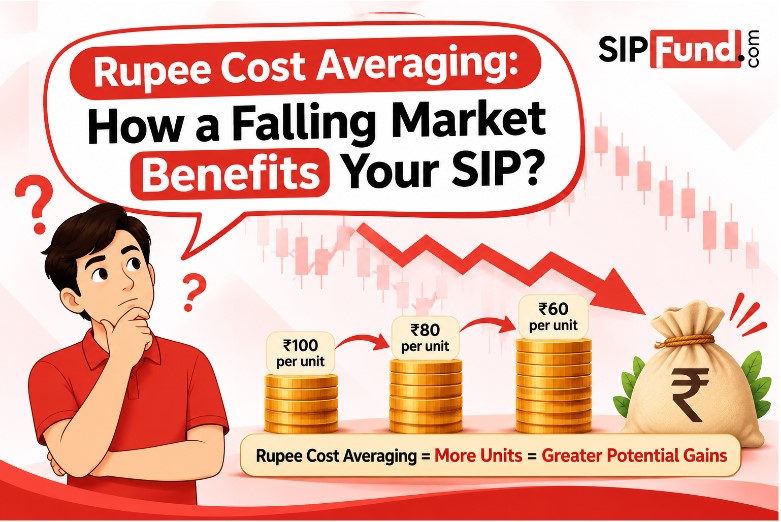
Rupee cost averaging means your fixed SIP amount buys more SIP units when prices fall and fewer when they rise. As the Nifty sits well below its peak, this habit turns market fear into a smoother average cost over time. Stay regular, continue SIP and let the market’s dips work for you.
It’s never easy to see your portfolio go red. As of 23 October, the Nifty 50 is over 14% off its all-time high in this market correction, and many investors are asking the one question that keeps them worried: Should I cancel my SIP? It’s a natural thought. It’s also when many good plans go down the drain.
This is a more relaxed perspective. You don’t have to guess the bottom in a SIP. It does so by the simple method of rupee cost averaging, which means that it makes it possible to get more SIP units for the same money when prices fall. After you understand how it works, a decline in the market doesn’t seem like a danger to your plan, it’s a part of it.
This guide will tell you what the market is doing, what your SIP units do when the prices go down and why it’s one of the best choices you can make to be regular. At SIP Fund, we help investors create plans for their goals, not the headlines of the day. You are not behind. You’re creating something, piece by piece.
The Meaning of Rupee Cost Averaging
Your SIP is a fixed sum invested on a fixed date irrespective of the market. If the price of a fund unit is high, then the number of SIP units purchased is less. The lower the price, the more that is purchased. The average cost per unit over time is not at the highest point, but rather somewhere in the middle of the high and low points.
That’s rupee cost averaging in a paragraph. It takes the toughest task in investing, that of predicting the best day to buy, off your plate. You don’t have to check charts every day in the morning. Just turn up every month! If you don’t know which funds to begin with, our algorithm-based fund selection can help you narrow the selection.
It also addresses a very human issue. When prices go up, we feel courageous. When prices drop, we are afraid. When left to our own devices, most of us tend to purchase more when we feel courageous and less when we feel frightened – the exact opposite of what we should do. An automatic SIP removes the “mood factor” from your decision so your plan continues even when your nerves don’t.
It’s Perfect for Busy, Day-to-Day Investors
Most people have a job, a family and a hundred other things on their mind. A SIP requests a single decision, once, and then operates in the background. The first step towards finding a SIP that suits your lifestyle is to determine the amount you can invest every month without any hassle.
More reading helps, too. Our blog has a Knowledge Center that explains SIP basics, the various types of funds and goal planning in simple terms so you can have confidence before you invest.
Why a SIP in a Falling Market Works in Your Favour
Three habits that come out of falling markets that cost investors dearly. The first is delay – waiting to begin when it is not so chaotic. The second is emotional selling, which is when a SIP is halted when a statement turns red. The third is the loss of discipline; missing a few payments because the excitement wears off. In the meantime, the prices in the shops continue to increase, and the money saved each year is worth less. Inflation doesn’t stop when the market does, and neither should your plan. A SIP in a falling market addresses all three issues by making your intention a habit.
The concern is legitimate, and so are the figures. According to Business Today, on 23 October 2026, the Nifty 50 was 14.31% lower from its all-time high, the Nifty Midcap 150 was 12.92% lower from its all-time high and Nifty Smallcap 100 was 12.13% lower from its all-time high. All 11 indices in its data were at least 11% below their highs.
The same report makes the point that’s important to you. If the markets fall, then the same SIP amount will result in more mutual fund units. It also includes a sincere disclaimer: This does not ensure any profits or prevent additional losses. Both are true and a mature investor has both.
Reduced Costs, Reduced Barriers to Entry
Valuations are part of the story. A Business Today market review in early October pointed out that the Nifty was trading at 17-18 times one-year forward earnings, versus 23-24 times in 2024. A lower multiple doesn’t call the bottom, but it does indicate that your monthly payment is purchasing lower valuations than it was two years ago. But it doesn’t mean the coming month is not as unpredictable, it just provides long-term investors with a rational reason to continue investing steadily rather than sitting on the sidelines. There is a price to sitting out, too, since you can only gain from a recovery if your funds are invested at the start.
The same reasoning is evident in recent experience. Business Standard, based on Sensex data till 21 October, found that the SIP’s losses were less over the past year due to more SIP units being allocated along the way. The analyst quoted there said that a sideways market aids the SIP investors, who purchase at different prices.
That is a SIP in a falling market doing its job. Your prices go down, your SIP units accumulate and your average price changes.
How Rupee Cost Averaging Works When Prices Are Continuously Declining
Prices don’t drop in a linear fashion and then conveniently on a specific date. The Business Today report examined previous corrections and determined that the average maximum drawdown was 23% and median was 15%. A 10% fall is not a bottom fall. It can go further before it recovers.
This is where your SIP does something quietly useful. With each fall, the next instalment purchases SIP units at a lower price than the previous one. The average price per unit falls, and then, when the price goes up, you have more units to be better off with. If prices rise rapidly, your previous units benefit as well. There’s no need to guess where the market is going next.
Make sure to set boundaries. Your existing units can stay below your average cost for a while, and a fall on paper becomes a real loss only if you sell. Rupee cost averaging does not guarantee profits and does not save a fund that was poorly selected in the first place. It’s not magic, it’s discipline.
The Real Danger Is Not the Market Correction, It’s Stopping Your SIP
The market correction does not affect long-term investors as much as what they do during the downturn. The most frequent error is to stop the SIP, go to cash and wait until things settle down. The problem is that when prices return to normal, they have already begun to rise, and the investor who waited for the calm misses the low-priced units that rupee cost averaging would have picked up.
Despite the volatility that is a part of investing, investors are tempted to get out of the market and go to cash, which is what Outlook Money has reported on in a Nifty 50 total return analysis from 2000 to 2026. The same study also showed that investors who held on to their stocks for five years after the market peaked had a much lower risk of a negative return and a higher likelihood of a double-digit return. These are not guarantees, but a lesson: Time in the market is more effective than timing. Waiting for a clear signal feels safe, but it is a gamble that the market will give you a clear signal and it rarely does.
Indian investors have done this to a large extent. On 11 November Business Standard reported that SIP inflows dipped marginally to ₹32,160 crore in October despite net equity inflows declining 14% due to profit booking and volatility. Millions of normal investors saw a market correction and decided to press on.
Is it ok to continue SIP if the screen is red? Yes, for most long-term goals as long as the goal is still years in the future and the fund is still appropriate.
A Step-by-Step Approach to Continue SIP During the Dip
It’s easier to stay invested with a plan than it is with willpower. The difference is in three habits.
Do Not Change the Date or the Amount
Don’t touch what is working. It’s better to pick a SIP date and amount that you can do without any stress than a SIP date and amount that you would pick on a red day. When funds are limited and you have to continue SIP for a few months, it is better to go for a smaller SIP than no SIP at all.
Measure the Value of Your SIP Based on Your Objective and Not This Week’s NAV
Ask one question: Do I have a different goal now? A market correction is not a change in destination if you’re saving for a child’s education or retirement 10 years or more in the future.
Have an Emergency Fund and Review Your Mix
Investors who are not comfortable with the equity exposure may also need to rebalance rather than switch the whole portfolio, the Business Today report adds. Having a separate emergency fund means that you will never have to sell units at the wrong time to pay a bill. When you’re not sure of your mix, consult an advisor who considers your entire plan, not just one fund.
Bottom Line: Let the Dip Work for You
Your SIP is a choice to create your future on your own terms and this is something to be proud of. A market correction will test that decision. Rupee cost averaging is the reason it can pass the test: your instalment keeps buying, your holding keeps growing and your plan keeps moving, while others wait for a certainty that never comes.
There is no need to time anything. You must begin, be consistent and allow time to take effect.
Ready to begin? Call SIP Fund today at +91 9513355661 or email info@sipfund.com. Our team will assist you to select the appropriate funds, determine the correct amount and kickstart your SIP journey with confidence.
Disclaimer: This information is not meant to be investment advice. Past performance is not indicative of future performance. Mutual fund investments are subject to market risks. Before investing, please read all documents relating to the scheme carefully and seek advice from a registered advisor.
Comments (0)
Want to join the discussion?
Log In to Comment